On this page
- The layers of the chain, and what each one actually earns
- Why I’d rather own EV supply chain stocks than the automakers
- Critical minerals: the foundation, and the most painful layer
- Cells, chemistry, and where the value is migrating
- Power semiconductors: my favorite corner of the chain
- Charging and the grid nobody wants to talk about
- How I actually size these positions
- Frequently asked questions
- The Bottom Line
I bought my first lithium miner near the top of a hype cycle and got my head handed to me. The thesis wasn’t wrong — the batteries did get built, the factories did open — but I’d confused a good story with a good entry price. That single mistake taught me more about electrification than any research note ever did.
EV supply chain stocks are the companies that mine, refine, and build the pieces inside an electric vehicle: lithium and nickel, cathode material, battery cells, power semiconductors, charging hardware. Owning them lets you participate in electrification without having to guess correctly which automaker survives the price war.
That distinction matters more than most people realize. Automakers are locked in a brutal fight on price, brand, and software. The companies feeding them raw material and components often sell to all of them — plus grid storage, consumer electronics, and defense. Different risk profile entirely.
The layers of the chain, and what each one actually earns
Here’s how I mentally file the sector before I look at a single ticker. Each layer has its own economics, its own cycle length, and its own way of disappointing you.
| Layer | What it does | Example names | My take on the risk |
|---|---|---|---|
| Mining & brine | Extracts lithium, nickel, cobalt, rare earths | Albemarle, SQM, Rio Tinto | Direct exposure to commodity prices. Violent swings both ways. |
| Refining & cathode | Turns ore into battery-grade chemicals and cathode powder | Ganfeng, Umicore, Posco | Better margins than mining, but heavily China-weighted. |
| Cells & packs | Builds the actual battery | Panasonic, LG Energy Solution, CATL, Tesla | Capital-hungry. Scale wins; subscale players bleed. |
| Power semiconductors | Inverters, onboard chargers, silicon carbide | ON Semiconductor, Infineon, STMicro, Wolfspeed | Highest-quality economics in the chain, in my view. |
| Charging & grid | Chargers, transformers, switchgear, cabling | ABB, Eaton, Schneider, ChargePoint | Slower story, steadier cash. Underrated. |
Figures and rankings inside each layer move constantly — check current filings before you act on any of it. What doesn’t move much is the shape: the further downstream you go from the dirt, the less your P&L swings with commodity prices.
Why I’d rather own EV supply chain stocks than the automakers
Three reasons, and none of them are complicated.
First, demand comes from more than one place. Lithium doesn’t care whether it ends up in a crossover, a utility-scale storage installation, or a data center backup system. That’s a real cushion. When passenger EV sales in a given quarter disappoint, grid storage has repeatedly picked up slack. Same logic extends to commercial fleets — I’ve written separately about electric bus stocks, and those buyers are municipal budgets, not fickle consumers.
Second, you avoid brand risk. Picking the winning EV brand is a coin flip dressed up as analysis. Picking the company that supplies silicon carbide inverters to six of them is a much easier bet.
Third, the switching costs are real. Qualifying a new cathode supplier or a new power module into a vehicle platform takes years of testing. Once you’re designed in, you’re sticky. That’s the kind of moat I actually pay up for.
The counterargument, which I take seriously: suppliers get squeezed. Automakers under margin pressure push that pressure straight up the chain. Contract renegotiations in this industry are not gentle.
Critical minerals: the foundation, and the most painful layer
Lithium
Lithium is the one input essentially every current battery chemistry needs. That makes producers like Albemarle and SQM the base of the pyramid — and also the most cyclical thing in the sector.
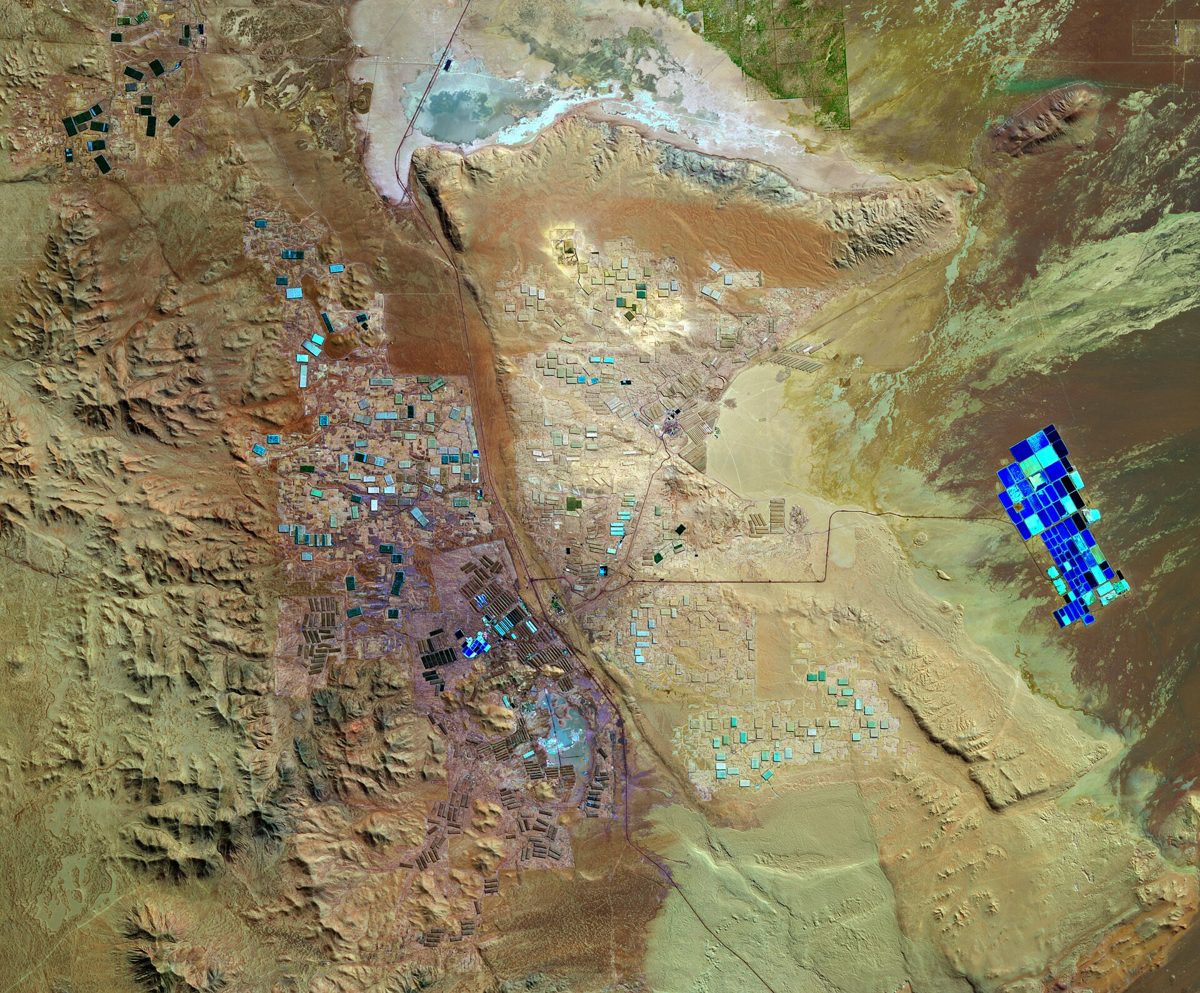
Albemarle’s pitch is diversification: brine in Chile, hard rock in Australia, processing on several continents. Customers pay for that resilience. SQM’s advantage is the Salar de Atacama, one of the lowest-cost brine resources on earth, though it comes bundled with Chilean political and royalty risk that flares up periodically.
Rio Tinto completed its acquisition of Arcadium Lithium for roughly $6.7 billion — check the final terms, since these deals get restated — which told me something important. A diversified major with plenty of alternatives chose to buy into lithium at a moment when sentiment was poor. Majors don’t usually do that for fun.
My honest read: lithium spot prices went through a deep, ugly drawdown, and the recovery has been uneven. Storage demand has grown fast enough that several producers now guide to demand outpacing supply again — but I’d treat any specific growth percentage you read as a moving target and verify it against the latest company guidance. Buy lithium producers when the headlines are miserable, not when they’re euphoric. I learned that the expensive way.
Nickel, cobalt, and manganese
Cell chemistry decides who wins here. High-nickel cathodes deliver the energy density premium vehicles need, so nickel demand tracks the top end of the market. Cobalt is the one everybody’s been engineering out — both for cost and for the sourcing controversies around Democratic Republic of Congo production.
Meanwhile LFP — lithium iron phosphate — has taken enormous share in standard-range vehicles and in stationary storage. LFP uses no nickel and no cobalt. If you own a nickel-levered name purely on an EV thesis, you should understand that chemistry mix is actively working against you in the volume segment. That’s a structural headwind, not a cyclical one.
Rare earths and permanent magnets
EV traction motors need permanent magnets, and those magnets need neodymium and praseodymium. China dominates both mining and — more critically — the separation and processing steps. Concentration like that is a geopolitical pressure point, and it’s been used as one.
Western governments have responded with funding for alternative sources, magnet plants, and recycling. Companies building non-Chinese rare earth capacity have a genuine strategic tailwind. They also tend to be pre-revenue or barely profitable, which means you’re underwriting execution and policy, not earnings. Size those positions accordingly.
Cells, chemistry, and where the value is migrating
The pack is the single most expensive component in an EV, usually a substantial share of total vehicle cost. Cell manufacturing is a scale game with punishing capital intensity: multi-billion-dollar plants, long ramps, yield problems that take quarters to fix.
What I watch isn’t headline capacity — it’s yield and utilization. A gigafactory running poorly destroys more capital than a smaller one running well. When a cell maker starts talking vaguely about “ramp timing,” I get cautious.
Solid-state batteries are the wildcard. If they commercialize at scale, the winners capture enormous value and several incumbent cathode and separator suppliers get disrupted. Timelines have slipped repeatedly. I own zero of my portfolio on the assumption solid-state arrives on schedule — if it shows up early, that’s upside I didn’t pay for.
Power semiconductors: my favorite corner of the chain
Every EV needs an inverter to convert DC battery power to AC for the motor, plus an onboard charger and a DC-DC converter. Silicon carbide handles high voltage more efficiently than plain silicon, which translates directly into range — the single spec buyers care most about.
Why I like this layer: gross margins are structurally higher than mining, design-in cycles create multi-year revenue visibility, and the same chips serve industrial, solar, and grid applications. ON Semiconductor, Infineon, and STMicroelectronics all have real positions. Wolfspeed is the pure play, and it’s been a much rougher ride — a reminder that being early to the right technology and being a good investment are separate things.
The risk is oversupply. Everyone announced silicon carbide capacity at the same time. Pricing has already felt it. If you’re screening this layer alongside the broader theme, my roundup of the best clean energy growth stocks covers how I compare these against solar and storage names on the same criteria.
Charging and the grid nobody wants to talk about
Here’s the part that gets skipped in most EV articles. Charging infrastructure is only half the problem. The other half is that distribution networks in much of the country were not designed for millions of vehicles pulling power at once. Transformers, substations, switchgear, high-voltage cable — that’s where a lot of the actual spending lands.
Pure-play charging network operators have been, frankly, difficult investments. Heavy capital needs, thin unit economics, competition from automakers building their own networks. The picks-and-shovels electrical equipment suppliers have generally done better. I go deeper on that in my piece on grid modernization, and it’s the part of the theme I’d argue is most persistently underestimated.
How I actually size these positions
A few rules I follow, learned mostly through losses.
- Cap the whole theme. These names correlate hard with each other. Five EV supply chain positions is not five positions — it’s one big one wearing a disguise.
- Weight toward the profitable layers. Semis and electrical equipment get more of my capital than pre-revenue miners.
- Buy miners into pessimism. Commodity producers are the one place where the ugliest headlines have historically been the better entries.
- Check customer concentration. A supplier deriving most revenue from one automaker isn’t a diversified bet — it’s a levered one.
- Watch policy, don’t depend on it. Credits, tariffs, and sourcing rules shift with elections. A thesis that only works with a specific subsidy intact is fragile.
If you’re building a broader portfolio and want to see where this theme sits against other ideas, my list of the best growth stocks to buy in 2026 puts it in context. And if sourcing ethics matter to you — cobalt labor conditions, water use in Chilean brine operations, mine tailings — that’s worth reading alongside my notes on sustainable investing, because the tension between “clean vehicle” and “dirty extraction” is real and doesn’t have a tidy resolution.
Frequently asked questions
Are EV supply chain stocks safer than buying EV makers directly?
Safer isn’t the right word — different. Suppliers avoid single-brand risk and often sell into storage and industrial markets too. But mining names are extremely cyclical and can fall harder than automakers in a downturn. You’re trading brand risk for commodity and capital-intensity risk.
Does LFP battery chemistry hurt the investment case?
It reshapes it. LFP removes nickel and cobalt demand, which pressures those miners, while keeping lithium demand fully intact. It also lowers pack costs, which supports total EV volumes. Net effect: good for lithium and semis, structurally negative for cobalt-levered names.
What’s the biggest risk in this sector right now?
Overcapacity. Lithium refining, cell plants, and silicon carbide fabs were all announced during the same enthusiasm wave. When too much supply arrives at once, prices fall and margins compress across several layers simultaneously. That’s a bigger near-term threat than demand disappointing.
How exposed are these companies to China?
Very. China dominates refining, cathode production, and rare earth processing regardless of where the raw ore is mined. Export controls and tariffs cut both directions. Western names building non-Chinese capacity get a policy tailwind, but many are still unprofitable and dependent on government support.
Should I use an ETF instead of individual names?
For most people, probably yes. Thematic battery and clean-tech ETFs spread you across mining, cells, and components without requiring you to judge cathode chemistry. You give up upside from picking well, and some funds carry heavy China weightings — read the holdings before you buy.
The Bottom Line
I still own pieces of this chain, and I expect to for a long time. But my allocation looks nothing like it did during that first painful lithium trade. Less dirt, more silicon. Less story, more cash flow. The electrification of transport is a decades-long build-out, and build-outs reward suppliers who survive the overcapacity phase — which means the boring, profitable, diversified names usually beat the exciting pure plays. Buy the cyclicals when everyone’s bored of them. Keep the total theme small enough that being early doesn’t wreck you.
Last updated: August 2026. Figures are approximate and change — confirm current data before investing. Educational only, not individual investment advice.