On this page
I bought my first hydrogen stock in early 2021, right at the peak of the clean-energy frenzy. I told myself I was early to a once-in-a-generation shift. What I was actually doing was paying a perfect price for a wildly imperfect timeline. The position got cut in half, then in half again. That bruise taught me more about this corner of the market than any analyst report ever has.
So when I write about hydrogen now, I write as someone who got burned and stuck around to figure out why.
Here’s the short answer. Hydrogen fuel cells are devices that turn hydrogen and oxygen into electricity through an electrochemical reaction, giving off only water and heat. For growth investors, the opportunity spans the companies that make the fuel cells, the firms producing clean hydrogen, and the businesses building the storage and refueling infrastructure to move it all around.
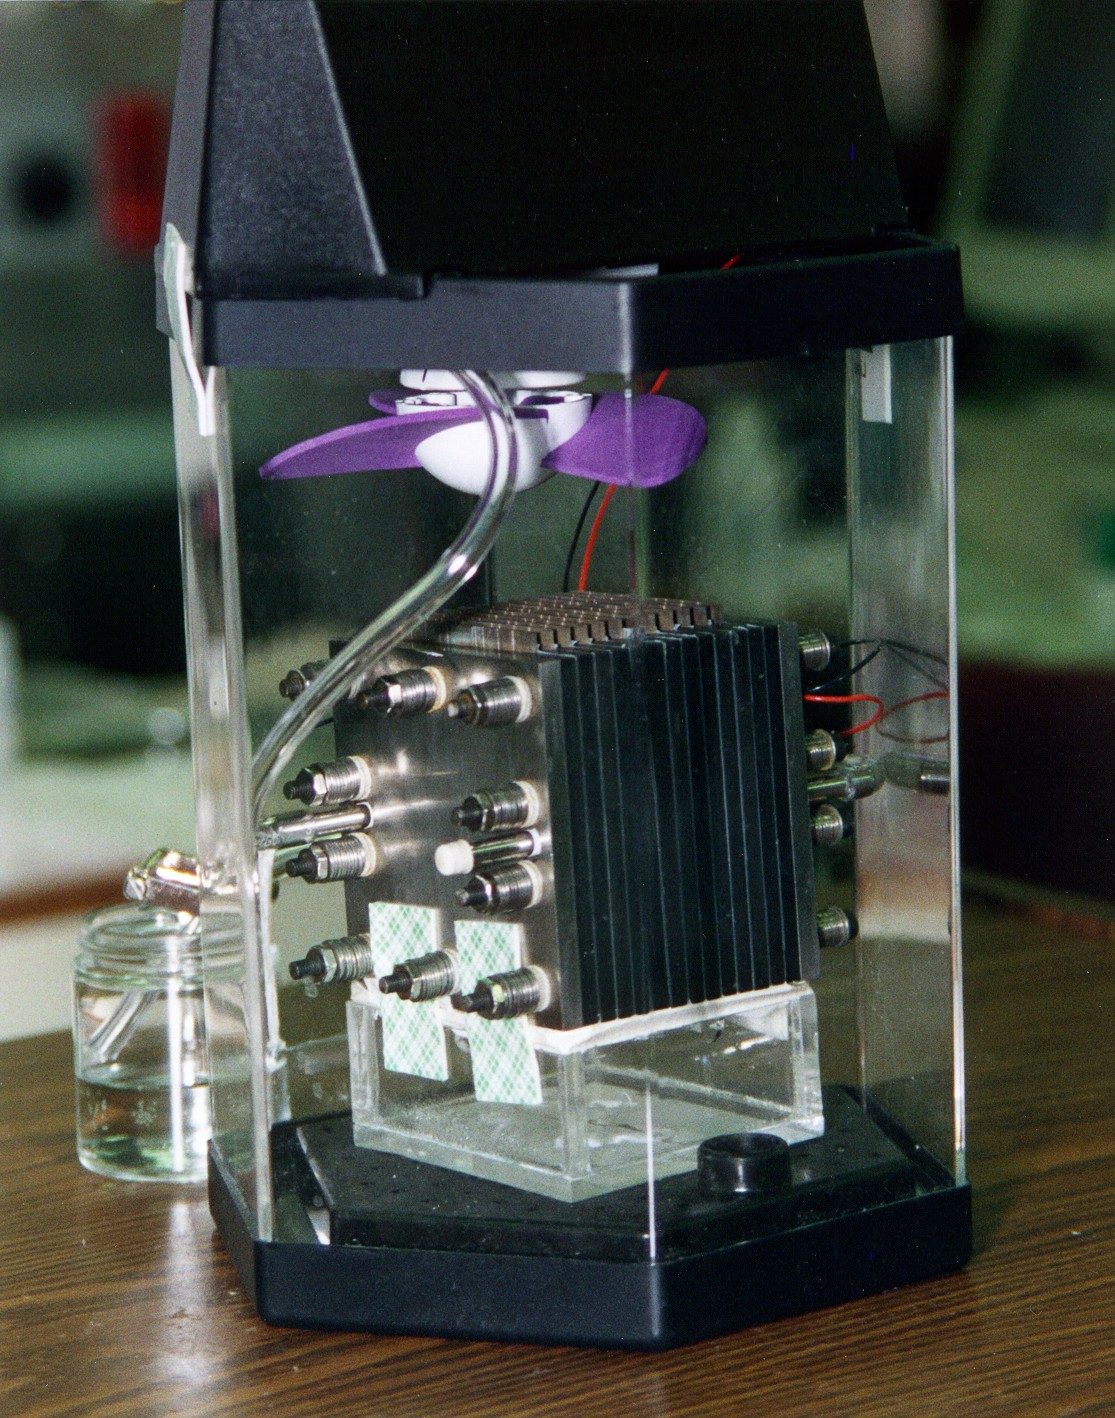
The thing I keep coming back to is that hydrogen isn’t trying to beat batteries at everything. It’s aiming at the jobs batteries do badly: long-haul trucking, ships, steel mills, backup power, and storing energy for days instead of hours. That’s a real niche. Whether any single stock turns that niche into durable profit is the whole game, and honestly, most of them haven’t yet.
Why hydrogen fuel cells matter for growth investors
Batteries won the car. That’s settled in my mind. A lithium pack is just more efficient for a commuter sedan, and the charging network keeps getting better. If you want exposure to that side of the energy transition, my roundup of the Best Battery Stocks is where I’d point you first.
But a battery big enough to push an 80,000-pound truck across three states would weigh a ton you can’t afford to haul, and it would take hours to recharge. That’s where hydrogen has an opening. You can refuel a fuel-cell truck in roughly the time it takes to fill a diesel tank, and the cell itself is light. Same logic applies to forklifts running three shifts in a warehouse, to data-center backup power, and to industrial heat that electricity struggles to deliver.
The money behind this is not small. Government programs in the U.S. and Europe have committed enormous sums to clean hydrogen, and the production tax credits in the Inflation Reduction Act are designed specifically to close the cost gap between dirty and clean hydrogen. That policy tailwind is real. It’s also the single biggest risk, because a future administration could weaken those credits and pull the rug out. I never forget that the subsidy and the thesis are tied together.
The hydrogen value chain, broken into pieces
I stopped thinking about “hydrogen” as one industry a while ago. It’s at least three different businesses stacked on top of each other, and each one has its own economics and its own odds of paying off. Here’s how I split it before I look at a single ticker.
| Segment | What they do | Example players | My read on the risk |
|---|---|---|---|
| Fuel cell makers | Build the stacks that turn hydrogen into electricity | Plug Power, Ballard Power, Bloom Energy | High burn, profitability still elusive |
| Electrolyzer / production | Split water with renewable power to make green hydrogen | Plug Power, Nel ASA, Cummins | Cost gap is the make-or-break variable |
| Industrial gas giants | Produce and distribute hydrogen at massive scale today | Linde, Air Products, Air Liquide | Lower risk, profitable, hydrogen is one slice |
| Heavy-duty vehicles | Build hydrogen trucks, buses, and powertrains | Nikola (defunct), Hyzon, legacy OEMs | Brutal; many have failed outright |
| Fueling infrastructure | Storage, compression, and refueling stations | Mix of startups and the gas majors | Early, capital-hungry, chicken-and-egg |
Tickers and players move, and at least one name on that list has already gone bankrupt, so confirm current data before you act on any of it. The point of the table isn’t a buy list. It’s to show you that “investing in hydrogen fuel cells” can mean five very different bets, with five very different risk profiles.
The colors of hydrogen, and why they matter to your wallet
You can’t size up this industry without understanding the color codes, because they decide the economics. Gray hydrogen comes from natural gas and makes up most production today. It’s the cheapest and the dirtiest. Blue hydrogen is the same process with carbon capture bolted on, which cuts emissions at a moderate cost premium. Green hydrogen is made by splitting water with renewable electricity. It’s the clean dream, and right now it’s also the most expensive by a wide margin.
That cost gap is the central drama of the whole sector. Green hydrogen needs to get a lot cheaper, or the subsidies need to stay generous, or both. Renewable power keeps getting cheaper and electrolyzers keep improving, so the gap is closing. But “closing” and “closed” are very different things for a company trying to turn a profit this decade. I read every green-hydrogen pitch with that gap front of mind.
Fuel cell makers, the pure-play bet
These are the names most people mean when they say “hydrogen stocks.” Plug Power, Ballard Power, and Bloom Energy build the fuel-cell stacks themselves. They’re the purest way to bet on the technology, and they’re also where I’ve seen the most pain.
My honest take: this segment has been rough on investors for years. Many of these companies have grown revenue while still losing money on nearly every unit they ship, funding the gap by issuing stock and diluting the people who already own it. The technology genuinely works. The business model of selling it profitably at scale is the part that keeps slipping. I treat the pure-plays as the highest-risk, highest-reward corner here, the place where you can be completely right about hydrogen’s future and still lose money on the wrong stock.
Industrial gas giants, the boring way in
This is the layer I find most comfortable, and it’s the one beginners overlook. Companies like Linde, Air Products, and Air Liquide already produce and ship industrial hydrogen at enormous scale, profitably, today. Hydrogen for the energy transition is an add-on to a business that already makes money selling gases to refineries, factories, and hospitals.
It’s the classic “sell picks and shovels” approach. You don’t have to guess which fuel-cell startup wins; you just need the broader hydrogen economy to keep expanding, and these firms supply the molecule no matter who comes out on top. The trade-off is obvious: far less explosive upside than a pure-play. But I sleep better owning a profitable company with a hydrogen kicker than a cash-burner with a great story. If that philosophy resonates, my broader list of the Best Clean Energy Growth Stocks leans on exactly this kind of survivor-first thinking.
How I actually evaluate hydrogen fuel cells stocks
Theme investing is dangerous precisely because the story is so good. A clean fuel whose only exhaust is water? It practically sells itself, which is exactly why it’s so easy to overpay. So I force myself through a short checklist before I take any hydrogen name seriously.
- How long can it survive on its own cash? A company with years of runway can wait out delays. One burning its last pile of money cannot, and dilution will eat you alive.
- Is the revenue profitable, or just growing? Shipping more units at a loss is not a business. I want a credible path to positive gross margin.
- How dependent is the thesis on subsidies? If the whole case collapses when a tax credit expires, that’s a political bet as much as a business one.
- Where does it sit in the value chain? A profitable gas giant with a hydrogen arm carries far less single-bet risk than a lone fuel-cell startup.
- What am I paying for the dream? If the valuation already assumes flawless execution a decade out, the margin for error is gone.
That last point is the one that got me in 2021. The market had priced in a perfect future, and when reality ran even slightly behind schedule, the correction was savage. I’d rather pay a fair price for a messy timeline than a perfect price for a perfect one.
Don’t bet the whole portfolio on one theme
I keep hydrogen as one small slice of a diversified growth book, never the centerpiece. The timing here is genuinely hard to call, and “right idea, wrong decade” is a real way to lose real money. I’d rather hold a measured basket across the layers above, sized so a blowup in any single name stings without doing lasting damage. For the foundation I build around first, my list of the Best Growth Stocks to Buy in 2026 is where I start before sprinkling in higher-risk theme bets like this one.
Where hydrogen fits next to the rest of clean energy
Hydrogen doesn’t live in a vacuum. It’s one tool in a much larger transition, and some of the neighboring themes are further down the road to profit, which matters when you’re deciding where your next dollar goes.
Solar is the obvious partner. Cheap solar power is one of the main inputs that could finally make green hydrogen affordable, so the two themes are quietly linked, and my writeup on the Best Solar Stocks to Buy covers the supply side of that equation. On the demand side, passenger transport is mostly going electric, and the buildout of plugs and fast-chargers behind that shift is its own investable theme, which is why I keep an eye on EV Charging Stocks even though they compete with hydrogen for some of the same vehicles. Thinking across these themes is how I spot where one trend powers another, and where two of them are fighting over the same customer.
Frequently asked questions
Are hydrogen fuel cells a good investment in 2026?
It depends entirely on which part of the chain you mean. The technology is real and the policy support is substantial, but most pure-play fuel-cell stocks are still unprofitable and volatile. I’d treat them as a small, high-risk slice, and lean toward profitable industrial-gas players for steadier exposure. Always check current financials and cash runway before buying.
What’s the difference between hydrogen and battery-electric vehicles?
Batteries store electricity directly and dominate passenger cars thanks to efficiency and a growing charger network. Hydrogen fuel cells generate electricity on board from a tank of hydrogen, refuel in minutes, and stay light, which suits trucks, buses, and forklifts better than huge batteries. They’re complementary, not strictly rivals, each fitting where the other struggles.
Why did hydrogen stocks fall so hard after 2021?
Many surged during the clean-energy enthusiasm of 2020 and 2021 on valuations that priced in a flawless future. Then profitability stayed out of reach, companies kept diluting shareholders to fund losses, and policy uncertainty rose. The trend toward hydrogen was real, but the individual stock prices got far ahead of the actual businesses, so the correction was brutal.
What is green hydrogen and why does it cost more?
Green hydrogen is made by splitting water with renewable electricity, so it produces almost no carbon. It costs more than gray hydrogen from natural gas mainly because of expensive electrolyzers and the price of clean power. As renewable electricity gets cheaper and electrolyzer technology improves, that gap is narrowing, helped along by government production tax credits.
What’s the safest way to invest in hydrogen fuel cells?
I lean toward the established industrial-gas companies that already produce hydrogen profitably and treat the energy transition as upside rather than their whole reason to exist. That sidesteps the cash-burn risk of the pure-plays. Spreading across the value chain, or holding hydrogen as one slice of a diversified growth basket, lowers single-stock risk considerably.
The Bottom Line
Hydrogen fuel cells solve a genuine problem that batteries can’t easily touch, and the government money behind clean hydrogen is real. But the gap between “this technology works” and “this specific stock makes me money” is enormous, and I have the scar tissue to prove it. My approach now is to favor companies with profits or deep cash reserves, stay wary of names that survive only on subsidies and dilution, refuse to pay a perfect price for a perfect timeline, and keep the whole theme as one measured slice of a diversified portfolio. Get the position sizing right and you can take part in a real transformation without betting the farm on which player happens to win.
Blue hydrogen only counts as low-carbon if the CO2 actually goes somewhere, which makes carbon capture stocks a direct dependency of a large part of this market.
Last updated: June 2026. Figures are approximate and change — confirm current data before investing. Educational only, not individual investment advice.