On this page
- A quick comparison of the major EV charging stocks
- How EV charging actually makes money
- The NEVI funding and policy tailwind
- The NACS standard is quietly reshaping the market
- How EV charging fits the rest of the clean-energy puzzle
- The risks I weigh before buying any EV charging stock
- Frequently asked questions
- The Bottom Line
The first time I tried to fast-charge a rented EV on a road trip, I spent twenty minutes hunting for a working plug, downloaded two apps, and ended up paying with a credit card at a beat-up kiosk. That experience told me more about this industry than any earnings call ever could. The hardware works. The business of running it is the hard part.
I’ve watched EV charging stocks swing from market darlings to deeply unloved names and back. So when people ask me whether this is finally an investable theme, my honest answer is “yes, but be picky.” This sector punishes lazy buying.
So what is EV charging as an investment? EV charging is the business of building and operating the plugs and networks that refuel electric cars, sold through hardware, software, and per-session revenue. For growth investors it’s a long-runway infrastructure buildout funded by government dollars and rising EV sales, but profitability remains uneven across the major players.
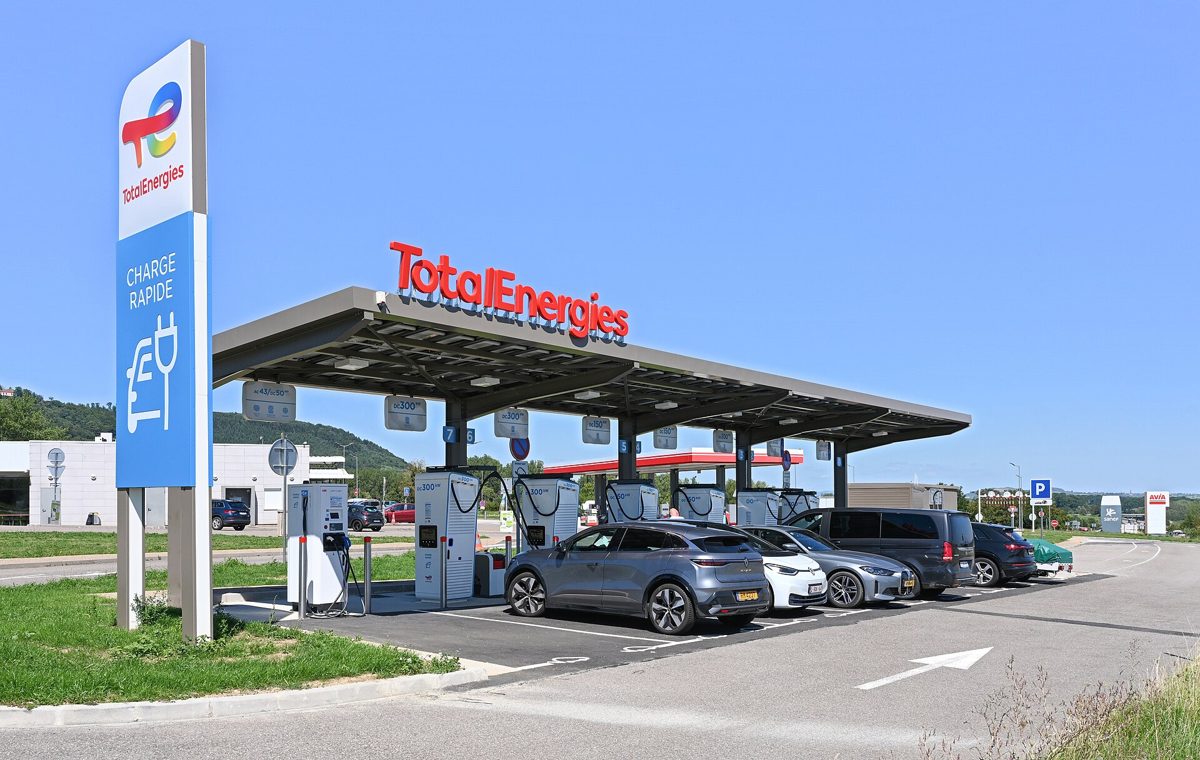
Below I’ll walk through the main public names, how their business models actually differ, where the money comes from, and the risks I weigh before touching any of these. I’ll keep the figures rough on purpose, because they move fast and you should always check current data yourself.
A quick comparison of the major EV charging stocks
Here’s how I bucket the better-known publicly traded names. Treat the figures as ballpark and directional, not precise. Verify current numbers before you act.
| Company (Ticker) | Primary model | Charging focus | What I like | What worries me |
|---|---|---|---|---|
| ChargePoint (CHPT) | Hardware + network software (capital-light) | Mostly Level 2, commercial and fleet | Large installed base, recurring software revenue | Slim margins, history of cash burn |
| EVgo (EVGO) | Owner-operator of public stations | DC fast charging, urban | NACS-first strategy, utilization climbing | Capital-intensive, leans on partnerships and funding |
| Tesla (TSLA) | Integrated Supercharger network | DC fast charging, owns the NACS standard | Best network, profitable parent company | Charging is a small slice of the overall story |
| Blink Charging (BLNK) | Mixed owner-operator + hardware sales | Level 2 and some DC fast charging | Owns hardware, broad footprint | Small scale, persistent losses |
| BP / Shell (BP, SHEL) | Oil majors building charging arms | DC fast charging at fuel sites | Deep pockets, prime real estate | Charging is a rounding error on their balance sheets |
Notice the trade-off running through that table. The pure-play names give you concentrated exposure but carry real financial fragility. The big diversified players are safer but barely move on charging news. That tension is the whole game here.
How EV charging actually makes money
If you only remember one thing, remember this: charging revenue and charging profit are very different animals. A station can be busy and still lose money once you account for hardware, electricity, maintenance, and the cost of capital. For years that gap is what wrecked the sector’s reputation.
There are a few core ways these companies earn:
- Per-session charging fees. Drivers pay to plug in. This is the most intuitive model and the most capital-hungry, because someone has to own and maintain the hardware.
- Hardware sales. Selling chargers to businesses, fleets, and property owners. Lumpy revenue, but real cash up front.
- Network software and services. Recurring subscription fees for managing chargers someone else owns. Lower revenue per unit, but higher margins and stickier.
- Fleet and commercial contracts. Long-term deals to electrify delivery vans, buses, and corporate fleets. I think this is one of the more underrated growth lanes.
My take: the software and services piece is what separates the survivors from the also-rans. A company that owns the network relationship can keep earning long after the hardware is installed. That’s a better business than pouring concrete and praying for utilization.
Charging levels and why they matter for investors
Charging splits into three tiers, and each maps to a different investment story.
- Level 1 uses a standard household outlet and adds maybe 3 to 5 miles of range per hour. Fine for overnight at home, irrelevant commercially.
- Level 2 runs on 240 volts and adds roughly 15 to 40 miles per hour. This is the workhorse for offices, apartments, and retail. Cheaper to deploy, lower revenue per session.
- DC fast charging (Level 3) can add 100 to 200-plus miles in 20 to 30 minutes. It’s the closest thing to a gas station refuel, commands the highest per-session revenue, and costs the most to build.
So when you read about a company’s “station count,” dig one layer deeper. A thousand Level 2 plugs and a thousand DC fast chargers are not remotely the same business. The capital, the revenue, and the competitive moat all look different.
The NEVI funding and policy tailwind
Government money is a huge part of this story, and it’s also where I’d urge the most caution. The National Electric Vehicle Infrastructure program, usually shortened to NEVI, has steered billions of dollars toward building out charging along highway corridors. When the program is actively contracting, it’s a meaningful tailwind for the operators positioned to win those bids.
But policy cuts both ways. Funding can be paused, redirected, or tangled in red tape, and that uncertainty has whipsawed these stocks before. I never build an investment thesis that depends entirely on a subsidy staying generous. If a charging company only works because Washington is writing checks, that’s a flashing warning light, not a moat.
For the broader policy and clean-energy context, I lean on our roundup of the Best Clean Energy Growth Stocks, which frames where charging sits inside the wider energy transition.
The NACS standard is quietly reshaping the market
One of the most important shifts of the past few years is boring on the surface: connector standardization. The industry has consolidated around the North American Charging Standard, or NACS, the connector Tesla originally designed. Nearly every major automaker has adopted it.
Why does a plug shape matter to your portfolio? Because fragmentation used to be a real drag on adoption. Drivers worried about compatibility, and operators hedged their hardware bets. NACS removes a lot of that friction. EVgo, for one, has pushed a NACS-first strategy and committed to rolling out a large batch of NACS connectors.
The flip side is that standardization tilts the field toward Tesla, which owns the standard and runs the most reliable network. That’s great if you hold Tesla and a little uncomfortable if you’re betting on a smaller rival to out-execute it.
How EV charging fits the rest of the clean-energy puzzle
I rarely look at charging in isolation. It’s one node in a bigger electrification web, and the adjacent themes often tell you more about demand than the chargers themselves.
The most direct link is batteries. Cheaper, denser batteries mean more EVs on the road, which means more charging demand. If you want to go upstream, our guide to the Best Battery Stocks covers the cell makers and materials suppliers feeding the whole chain.
Then there’s the question of where all that electricity comes from. Charging only stays “clean” if the grid behind it cleans up. That pulls in generation themes like our look at the Best Wind Energy Stocks, and the more speculative corner of Hydrogen Fuel Cell Stocks, which competes with battery EVs in heavy trucking even as it complements the broader transition.
Honestly, I find it more useful to think of charging as part of an energy ecosystem than as a standalone bet. The companies that thrive will ride demand created by everything around them.
Pure-play versus diversified exposure
Here’s the decision I keep coming back to. Do you want concentrated exposure or diversified exposure?
A pure-play like ChargePoint or EVgo gives you maximum upside if charging economics inflect. It also gives you maximum downside if they don’t, and several of these names have had to raise cash on unfavorable terms. A diversified route, owning Tesla or an oil major with a charging arm, blunts both the risk and the reward.
My personal lean is to size pure-plays small and treat them as high-risk, high-variance positions inside a broader portfolio. If you want ideas across sectors to balance them out, our list of the Best Growth Stocks to Buy in 2026 is where I’d start building that base.
The risks I weigh before buying any EV charging stock
I won’t sugarcoat it. This is one of the trickier corners of growth investing, and the risks are specific.
- Cash burn and dilution. Several pure-plays have spent years unprofitable. When they need money, they often issue stock, which dilutes existing holders. Watch the balance sheet closely.
- Policy dependence. A thesis propped up by subsidies can crack when the political winds shift.
- Utilization risk. Empty stations don’t pay for themselves. Until usage rates climb, the unit economics stay shaky.
- Competition from giants. Tesla and the oil majors can outspend the small operators almost indefinitely.
- Technology and standard shifts. The NACS transition was a positive surprise, but the next shift might not favor the company you own.
None of these are reasons to avoid the sector entirely. They’re reasons to demand a clear path to profitability and to keep your position sizing honest. I’d rather miss some upside than ride a serial-diluter to zero.
Frequently asked questions
Are EV charging stocks a good investment in 2026?
They can be, but selectively. The sector has matured past the early hype, and investors now reward profitability over raw station counts. I’d focus on companies with recurring software revenue or a credible path to positive cash flow, keep positions small, and always check current financials before buying, since conditions change quickly.
What is the difference between Level 2 and DC fast charging?
Level 2 runs on 240 volts and adds roughly 15 to 40 miles of range per hour, ideal for homes, offices, and retail. DC fast charging adds 100 to 200-plus miles in about 20 to 30 minutes, serving highways and urban hubs. Fast charging earns more per session but costs far more to build and maintain.
Which company has the best EV charging network?
By most measures Tesla’s Supercharger network leads on reliability, scale, and user experience, and it owns the NACS connector standard now adopted industry-wide. Among the pure-plays, EVgo and ChargePoint are the larger names. That said, “best network” and “best stock” aren’t the same thing, so weigh the underlying business too.
How does government funding affect EV charging stocks?
Programs like NEVI direct billions toward building charging infrastructure, which can boost operators winning those contracts. But the support is political and can be paused or redirected, which has rattled these stocks before. I treat subsidies as a tailwind, never the core thesis, and favor companies that could survive without the checks.
Is Tesla an EV charging stock?
Partly. Tesla runs the largest fast-charging network and owns the NACS standard, so it has real charging exposure. But charging is a small slice of a company dominated by vehicle sales, energy storage, and software. If you want concentrated charging exposure, Tesla dilutes it. If you want charging plus a profitable parent, it fits.
The Bottom Line
EV charging is a genuine long-term growth theme, but it’s one I approach with my eyes open. The demand runway is real, the policy support helps, and standardization around NACS has cleared a major roadblock. What hasn’t fully arrived is durable profitability across the pure-plays.
My approach: favor recurring-revenue and software-led models, keep speculative positions small, and lean on diversified names for ballast. Do the homework on each balance sheet, because in this sector the difference between a survivor and a stumble usually shows up there first.
The fastest-moving part of charging demand is not private cars but fleets, where depot charging is a procurement decision rather than a consumer one — electric bus stocks covers that end of it.
Last updated: June 2026. Figures are approximate and change — confirm current data before investing. Educational only, not individual investment advice.