On this page
I’ve watched this theme get hyped, crushed, and quietly rebuilt three times now. Every cycle starts the same way: a policy headline, a wave of press releases, and a lot of stocks that go up before anything gets built.
Here’s the short version. Carbon capture stocks are shares in companies that capture carbon dioxide from industrial exhaust or straight out of the air, then transport, store, or reuse it. The group spans oil majors, engineering firms, industrial gas suppliers, and a handful of small pure plays — and most of the pure plays don’t make money yet.
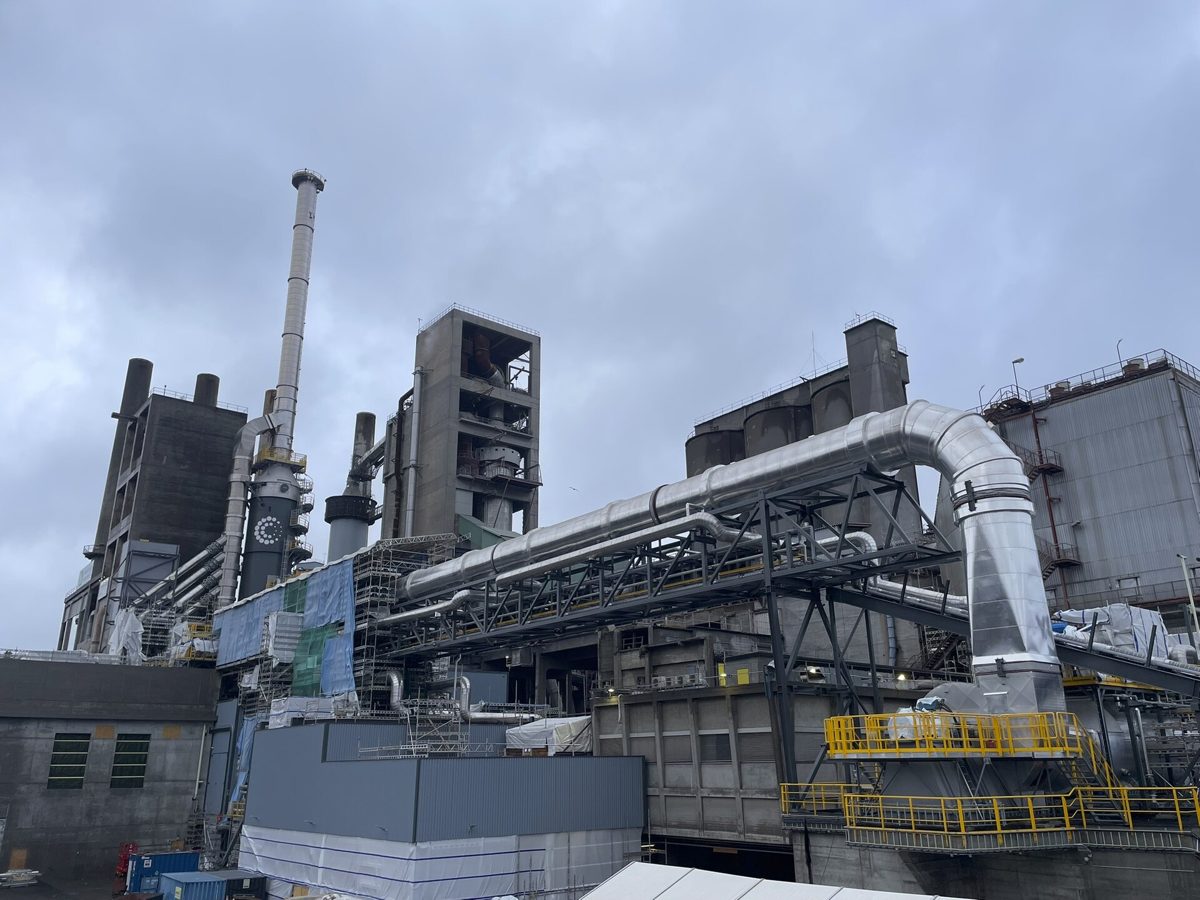
I want to be straight with you before we go further. This is the most policy-dependent theme I follow. Strip out the tax credits and a large share of these projects stop making financial sense overnight. That doesn’t make it uninvestable. It does mean you should size it like a bet, not like a core holding.
Why carbon capture exists at all
The honest case for the technology has nothing to do with cars or rooftops. It’s about the emissions nobody knows how to electrify.
Cement is the classic example. Making it releases CO2 from the chemistry itself, not just from the furnace, so you can’t fix it by plugging the plant into a wind farm. Same story with steel, ammonia, and refineries. Those industries aren’t going away, and the physics won’t budge. Either you capture the carbon or you accept the emissions.
That’s the part I find genuinely persuasive. It’s not a story about beating solar or batteries. It’s about the leftover emissions nothing else can reach.
The investing question is separate: does a durable, profitable business get built on top of that need, and can you buy it at a price that leaves room to be wrong? “The world needs this” and “this stock will make me money” are two different sentences.
The value chain, broken into pieces
I stopped thinking about carbon capture as one industry a while ago. It’s four or five separate businesses with very different economics stacked under one label, and lumping them together is how people end up owning something they never intended to own.
| Segment | What they actually do | Example names | My read on the risk |
|---|---|---|---|
| Point-source capture tech | Strip CO2 from industrial flue gas before it escapes | Honeywell, SLB, Baker Hughes, Aker/SLB Capturi | Moderate — capture is a small slice of a bigger business |
| Direct air capture | Pull CO2 out of ambient air | Occidental (1PointFive), Climeworks and Heirloom (private) | High — costly, unproven at scale, mostly not public |
| Transport and storage | Pipelines and permanent geological sequestration | ExxonMobil, Occidental, Talos Energy | Permitting and local opposition are the real hurdles |
| Equipment and engineering | Compressors, cryogenics, EPC contracts, plant builds | Chart Industries, Fluor, Linde, Air Products | Lower — profitable today, carbon capture is upside |
| Carbon utilization | Turn captured CO2 into fuels, chemicals, concrete | LanzaTech, plus many private startups | Very high — small caps, heavy cash burn |
Ownership shifts fast here — companies get acquired and joint ventures get renamed, so confirm current structure and financials before acting on any of it. The table isn’t a buy list. It’s there to show you that “investing in carbon capture” can mean five very different bets.
Point-source capture: the grown-up end
This is the mature corner. You bolt equipment onto a facility that’s already emitting and scrub the CO2 out of the exhaust stream before it hits the atmosphere. Plants have been doing versions of this for decades, mostly in natural gas processing where the CO2 is already concentrated and easy to separate.
Concentration is everything to the economics. A gas processing plant or an ethanol facility produces a nearly pure CO2 stream, so capture is comparatively cheap. A cement kiln produces a dilute stream full of nitrogen, and separating CO2 out of that mess takes far more energy. That’s why the tax credit matters far more to some projects than others.
What I like here is that the companies selling the equipment have other businesses paying the bills. Honeywell, SLB, and Baker Hughes aren’t betting their existence on carbon capture. If the theme runs ten years late, they’ll still be here.
Direct air capture: the expensive moonshot
Direct air capture, or DAC, pulls CO2 from open air rather than from a smokestack. Atmospheric CO2 is measured in parts per million, so you’re processing enormous volumes of air for a small amount of carbon. That makes DAC far more energy-hungry and more expensive per ton than point-source capture. Published cost estimates vary widely and keep moving, so check current numbers.
The appeal is that DAC removes historical emissions, not just new ones. That’s why buyers like Microsoft, Google, and Stripe have paid a premium for high-quality removal credits. Occidental Petroleum is the highest-profile public way to play it, through its 1PointFive subsidiary and Stratos project in Texas. Shell has backed DAC startups, and the Department of Energy has committed serious money to regional DAC hubs.
My candid view: DAC is a fascinating technology and a rough investment right now. The cost curve has to fall enormously for it to work without subsidy, and most of the interesting companies are private. Buying Occidental for DAC exposure means buying an oil producer whose share price mostly tracks crude, with a removal option attached. That may be fine. Just know what you’re holding.
Storage, pipelines, and the part nobody talks about
Capturing CO2 is only half the job. You then have to move it and put it somewhere permanent, usually deep saline formations or depleted oil and gas reservoirs. That means pipelines, injection wells, and Class VI permits from regulators.
This is where projects die quietly. Pipeline routes cross farmland and towns, landowners fight them, and permits take years. Several high-profile CO2 pipeline proposals in the Midwest have run into fierce local opposition. Ask where a project’s CO2 goes and whether that pathway is actually permitted. A capture plant with nowhere to send its carbon is an expensive sculpture.
The flip side is that whoever controls storage capacity and pipeline right-of-way owns something genuinely scarce. ExxonMobil bought Denbury largely for its CO2 pipeline network, which tells you what the industry thinks that infrastructure is worth.
The policy engine — and the reason I stay nervous
The U.S. 45Q tax credit is the most important number in this industry. It pays operators a set amount per metric ton of CO2 captured and permanently stored, with rates varying by whether the carbon is sequestered, used, or pulled from the air. Headline figures have run around $85 per ton for point-source storage, with higher rates historically applied to direct air capture, but Congress has amended these provisions more than once. Check the current statute before building a thesis on any rate.
Europe’s Carbon Border Adjustment Mechanism is the other lever. It puts a cost on the embedded emissions in imported steel, cement, aluminum, and fertilizer, moving from a reporting phase into real financial obligations. If it holds, European heavy industry faces genuine pressure to decarbonize rather than offshore. Timelines and scope have shifted before, so verify where it stands.
Here’s my worry, stated plainly. A tax credit is a political object. Administrations change, budgets change, and a credit that exists today can be trimmed or repealed. When a project’s entire return depends on a per-ton payment from the government, you’re underwriting political risk as much as engineering risk. Price accordingly.
How I evaluate carbon capture stocks
The story here sells itself, which is exactly why it’s easy to overpay. I force myself through the same short checklist before I take any name in this space seriously.
- Is there a real business underneath? I strongly prefer companies where carbon capture is upside on top of a profitable core, not the whole reason they exist.
- How much cash runway is left? Pre-profit names funding losses with new share issuance will dilute you while you wait. Check the burn rate and the share count trend.
- What happens if the tax credit disappears? If the answer is “nothing works,” that’s a policy bet wearing a technology costume.
- Are there signed offtake contracts? A binding agreement to buy captured carbon or removal credits is worth ten memorandums of understanding.
- Where does the CO2 physically go? Permitted storage and secured transport separate real projects from announcements.
- What’s already in the price? If the valuation assumes flawless execution a decade out, your margin for error is gone.
The bear case, which I think deserves respect
Let me argue against my own theme for a moment, because the skeptics have decent points.
Capture is expensive, and for most emitters it’s cheaper to keep emitting unless someone forces the issue. Much of the captured CO2 historically went into enhanced oil recovery, meaning it was used to produce more oil — which critics reasonably call a wash. Projects get announced and cancelled at a high rate, several flagship facilities have missed their capture targets, and the pure-play public companies are small, illiquid, and burning cash.
None of that means the theme fails. It does mean I keep position sizes modest and lean toward companies that survive if the timeline slips by a decade.
Where this fits alongside the rest of the energy transition
Carbon capture doesn’t stand alone, and I’d rather own it as one line in a broader clean energy allocation than as a standalone conviction. My roundup of the best clean energy growth stocks is where I start, because it applies the same survivor-first filter across the whole sector.
A few neighboring themes matter directly here. Capture plants consume large amounts of power, and that power needs to be clean or you’ve defeated the purpose — which is part of why I’ve spent time on nuclear energy as a source of firm, carbon-free electricity. Balancing intermittent renewables against industrial loads that run around the clock is the job of energy storage, and moving all that power to where heavy industry actually sits depends on grid modernization, which I’d argue is the least glamorous and most reliably necessary piece of the entire transition.
None of those should replace your foundation. I build the core of a portfolio from established compounders — the kind of names in my list of the best growth stocks to buy in 2026 — and only then add speculative themes like this one around the edges.
Frequently asked questions
Are carbon capture stocks a good investment right now?
It depends which segment you mean. Equipment makers and industrial gas firms with profitable core businesses offer reasonable exposure with limited downside. Pure plays are speculative, unprofitable, and heavily dependent on tax credits staying in place. I treat the pure plays as a small, high-risk slice rather than a core position, and I check cash runway first.
What is the difference between carbon capture and direct air capture?
Point-source carbon capture strips CO2 from a concentrated industrial exhaust stream before it escapes, which is comparatively cheap and commercially proven. Direct air capture pulls CO2 out of open air at very low concentrations, costing substantially more per ton but removing historical emissions rather than just preventing new ones. Both are real; the economics differ enormously.
How does the 45Q tax credit affect these companies?
45Q pays a per-ton credit for CO2 that’s captured and permanently stored or used, and for many projects it’s the difference between profitable and pointless. Rates vary by capture type and have been amended by Congress more than once, so confirm the current figures. Heavy credit dependence is also the sector’s biggest political risk.
Which companies are the biggest players in carbon capture?
Occidental Petroleum is the most visible public name through its 1PointFive direct air capture arm. ExxonMobil holds significant CO2 pipeline and storage assets. Honeywell, SLB, Baker Hughes, Linde, Air Products, and Chart Industries supply technology and equipment. Many of the most innovative capture startups remain private. Ownership changes often — verify current holdings before investing.
What could go wrong with carbon capture investments?
Tax credits could be reduced or repealed. Projects get cancelled at a high rate, pipelines face local opposition and permitting delays, and several flagship plants have missed their capture targets. Pure plays may dilute shareholders repeatedly while waiting for scale. Costs may simply stay too high for capture to compete without ongoing public support.
The Bottom Line
The industrial logic here is sound. Cement, steel, and chemicals need something like this, and no amount of solar panels solves their chemistry. That’s why I keep watching the space instead of dismissing it.
But the investment case is far shakier than the environmental one. Most pure plays are pre-profit, the economics lean on credits politicians can rewrite, and the gap between an announced project and an operating one is wide. So I favor profitable companies where capture is upside rather than survival, insist on signed offtakes and permitted storage, and keep the whole theme as one small, deliberately sized slice. Get that discipline right and you can take part in a genuinely important technology without staking your portfolio on a tax credit.
Last updated: August 2026. Figures are approximate and change — confirm current data before investing. Educational only, not individual investment advice.